
Abstract
The counter-terrorist financing (CFT) and the anti-money laundering (AML) regime is one of the broadest systems of global regulatory governance which integrates commitments in the form of binding treaties, soft law standards, and transnational networks of enforcement. This paper follows its development since the disjointed structure of the 1980s to the modern day issues of digital finance. It shows that AML/CFT governance is a hybrid order, which combines hierarchical treaties, FATF soft law, regulatory networks, and reputational incentives, through doctrinal analysis of the Vienna Convention (1988), Palermo Convention (2000), UNCAC (2003), and the International Convention of the Suppression of the Financing of Terrorism (1999). Even though financial action taskforce (FATF) does not have a formal treaty power, it enjoys de facto normative power due to compliance pressures. Based on FATF mutual evaluation (2013-2024), the article identifies the continuous disparity between technical compliance and operational quality, especially in the developing states, and suggests a model of reform to reconcile the norm diffusion with the ability to substantially enforce the rules.
Keywords
AML & CFT, Legal Pluralism, Global Governance, Compliance Theory, Developing Economies.
Introduction
T
he evolution of world anti-money laundering (AML) and counter-terrorist financing (CFT) regulation over the past forty years has been an institutional revolution, including the shift in the structure of criminological responses to the issue into a complex multilayered regime that arguably represents the overall architecture of transnational financial regulation in the world today. The transformation did not happen as a result of formal diplomatic tools or through binding multilateral treaties, but as a dynamic interaction of hard law tools, soft law demands, transnational professional networks and market oriented reputational incentives all working together at the same time at more than one level of governance (UNODC, 2023). Until the late 1980s, money laundering (ML) was more of a criminological notion used in the study of organized crime as opposed to a legal category that needed to be dealt with in a coordinated international response (Mike, 2020). Early reporting requirements were established under the Bank Secrecy Act (1970) but were not related to proceeds concealment (Ambareen et al., 2023). Critically, no integrated international legal framework existed (Ambareen et al., 2023). Mutual legal assistance (MLA) was working on a bilateral basis; extradition systems could not be integrated; and financial crime was seen as an internal domestic issue despite the fast internationalization of banking networks and the spread of offshore financial centres.
The basic contradiction of this period of pre-normative fragmentation was that, although there was a general awareness of the transnational nature of financial crime and the disruptive impact on financial systems, states did not have common conceptual vocabularies, institutional means of coordinated response, and a single legal category of the illicit concealment of proceeds (FATF, 1990). The Vienna Convention against Illicit Traffic in Narcotic Drugs and Psychotropic Substances (1988) represented a turning point, making ML an independent criminal act and requiring state compliance with binding treaty obligations regarding criminalization (Vienna Convention, 1988). On the occasion of the Financial Action Task Force (FATF) that was formed in 1989 by the Group of seven (7) major economies, the regime was transformed into a soft law-based system but gained de facto binding power without ever being a treaty (Jason, 2008). After 9/11 securitization incorporated counter-terrorist financing, and AML and CFT expanded exponentially (UNODC, 2023). This development depicts one basic question of governance. What does an organization with no official treaty-making power do to attain regulatory convergence in 200+ jurisdictions? The modern topicality of the study of AML and CFT governance architecture is complex and acute. To start with, the estimated figures of ML in the world have increased exponentially including USD 2 to USD 2.5% of world GDP in the 1990s to USD 2.3 trillion in the world, a growth that has been driving organized crime, corruption, and black economies that destabilize the financial system and erode the rule of law around the world (UNODC, 2023).
Second, the channels of terrorist financing (TF) have been spreading and diversifying: alongside the old (state sponsorship, charitable contribution, legitimate business fronts) there are advanced networks deploying trade-based money laundering (TBML), hawala networks (estimated USD 100+ billion/year including licit flows), ransomware payments, and cryptocurrency ecosystems which are increasingly out of traditional banking regulation (UNODC, 2023). Chainalysis cautions that 2024 will be marked by records of illicit activity, with total amounts potentially topping USD 51bn (Chainalysis, 2024). In 2023, the original figure of 24.2 billion was amended at 46.1 billion because further transactions with criminals were identified, and it is a significant vulnerability in regulation (Chainalysis, 2024).
Third, and most importantly, there is an indication of a deep implementation gap. The mutual evaluation database published by FATF in 2013-2024 reveals what has been described as the "effectiveness paradox" wherein most jurisdictions score well on technical ratings (Largely Compliant or Compliant 66% globally), but the ratings on effectiveness are dismal (28% globally) (FATF, 2024). Two of 11 outcome areas in the world receive a rating of Substantial effectiveness (FATF, 2024). Such a mismatch between legal adoption or formal adoption and operational ability indicates that laws and institutional structures do not automatically translate to significant breakage to the flow of illicit finance (FATF, 2024).
In the case of developing countries and new economies, the pressure is urgent. The situation in Pakistan is indicative of these tensions, although legal changes have been made in response to the FATF pressure, there has been a lack of implementation reflected by inter agency coordination failures, resource limitations, and technological bottlenecks (FATF, 2024). These trends are observed in the jurisdictions of Southeast Asia, Africa, and the Caribbean (Sharman, 2011). FATF compliance regulatory burden cuts across institutional capacity limits, political economy issues (corruption, regulatory capture, limited budgets), and competing development priorities (Sharman, 2011). Although there is substantial literature about AML and CFT standards at the descriptive level, the critical theoretical gap is to be identified in the interpretation of the governance architecture in terms of the coherent system of hard law, soft law, and transnational networks (Halliday, Levi & Reuter, 2014). In the majority of scholarship, AML and CFT are treated in a descriptive listing of legal instruments, consideration of technical compliance indicators, or typological criminal analyses (Halliday, Levi & Reuter, 2014). There is limited literature on the structure of governance, normative authority, the mechanisms through which normative authority is exercised without formal coercive power, the political economy of norm diffusion, or tensions between regulatory legitimacy and effectiveness (Sharman, 2011).
In particular, little is known about: (1) the legal pluralism and transnational criminal law theory that explains the hybrid nature of AML and CFT (Halliday, Levi & Reuter, 2014); (2) compliance mechanisms that are not based on a rational cost-benefit analysis, such as constructivist norm internalization and professional socialization (Sharman, 2011); (3) the way soft law gains binding force through interrelations with hard law, market discipline, and institutional reputation (Turner, 2014); (4) substantive tensions between rapid norm change and due process guarantees (Pavlidis, 2022); (5) how sovereignty pressures are differentially manifest in the context of jurisdictional authority and regulatory autonomy (Case-Ruchala & Nance, 2020). According to Nicholas W. Turner, this method embraces quick adaptation to emerging threats, and FATF standards have attained a quasi-hard-law status because of high compliance rates and peer review (Turner, 2014). Pavlidis states that the FATF provides high standards of compliance with the frequency of assessments, but the system is experiencing serious challenges because of the constantly growing amount and difficulty of transactions across countries (Pavlidis, 2022). Pavlidis asks the question of where to go (Quo vadimus?), pointing to the dark sides that are mentioned or the unintended negative consequences of strict implementation of FATF standards (Pavlidis, 2022). He suggests that the future of the FATF depends on balancing its expansive standards with proportionality and a deeper understanding of the adverse socio-economic impacts of its policies (Pavlidis, 2022).
Subsequent researchers show that AML and CFT should be understood as a hybrid transnational order of governance whose binding impact cannot be determined solely on the basis of official sources (Halliday, Levi and Reuter, 2014). Halliday, Levi and Reuter theorize AML as a disciplinary transnational legal order, which demonstrates that regime power is accomplished when legal norms are engaged with institutionalized monitoring and implementation practices, but not treaty obligation alone (Halliday, Levi and Reuter, 2014). This redefines the puzzle of compliance that FATF itself formalizes as it separates technical compliance and effectiveness in mutual evaluations an institutional concrete of the central deficit that the regime manifests and replicates: finding rapid convergence in law on the books without equivalent convergence in outcomes (FATF, 2024). The diffusive studies, at that time, compromise the simple rationalist explanations of this convergence. The evidence presented by Sharman on the developing states indicates that the AML adoption is characterized by discursive power and externalizations of expectations, which means that the socialization of the profession and reputational vulnerability are constitutive but not residual compliance mechanisms (Sharman, 2011).
Lastly, the assertion that the soft law FATF creates becomes enforceable is one that should be approached analytically. According to Case-Ruchala and Nance, FATF blacklisting is a partial rational myth, which means that soft-law hardening relies equally on credibility, narrative, and market belief as on actual material compulsion, which is exactly where legitimacy and sovereignty tension is being structuralized within the AML and CFT governance (Case-Ruchala and Nance, 2020). The article fills these gaps by applying three coordinated theoretical frameworks, including doctrinal legal analysis, which describes the normative architecture as a form of formality; legal interpretivist analysis, which describes internalization and operationalization of norms; and compliance theory, which describes mechanism of change of state behavior when hierarchical authority is absent.
Understanding Hybrid Global Governance:
Legal Pluralism and Transnational Criminal Law Architecture
The legal pluralism offers the much-needed theoretical context to understand the AML and CFT governance. Instead of embracing a unified legal order derivable of sovereign state authority, pluralism characterizes transnational criminal law as comprising overlapping, intersecting and at times competing normative regimes in which state law coexists with other forms of soft law such as regulatory networks, professional norms, market discipline, and international law (Halliday, Levi & Reuter, 2014). AML and CFT represent the operation of transnational legal pluralism. They combine hard law (individual commitments of states to treaties: Vienna, Palermo, UNCAC, ICSFT conventions and treaty obligations), soft law (FATF Recommendations, interpretive notes, typologies, mutual evaluation frameworks), regulatory networks (FATF plenary, regional FSRBs, Financial Intelligence Units, supervisory colleges) and market discipline (correspondent banking restrictions, derisking, institutional liability) (FATF, 2024). These mechanisms operate both simultaneously and non-hierarchically, establishing what Teubner referred to as regime complexity, i.e., when several normative systems address overlapping regulatory issues without the existence of a central coordinating authority (Teubner, 2012). As Figure 1 illustrates, AML and CFT governance consists of interacting layers of hard law, soft law, regulatory networks and market discipline rather than a single hierarchical legal order (Halliday, Levi & Reuter, 2014; FATF, 2024).
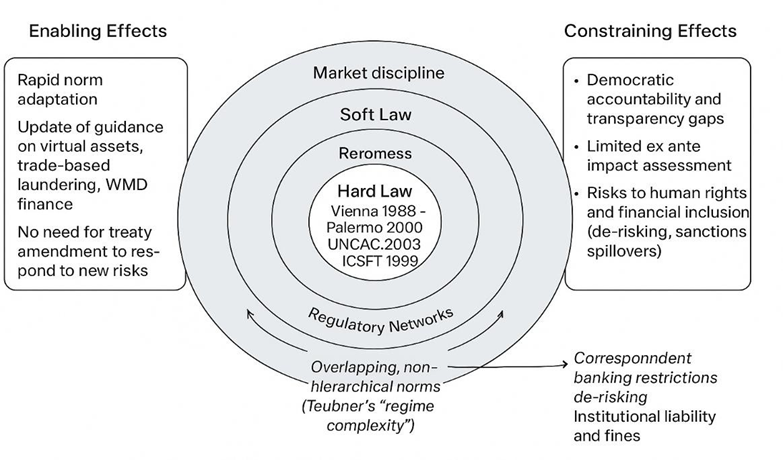
This pluralist architecture both enables and constrains governance. It enables rapid norm adaptation; for example, when the FATF identifies emerging threats such as virtual assets, trade-based money laundering, or the illicit financing of weapons of mass destruction, it can update its Recommendations and guidance without requiring laborious treaty amendment processes (FATF, 2023; Turner, 2014). This adaptability depicts the flexibility of transnational regulatory orders that are driven by soft-law and exist outside the bounds of formal treaties (Halliday, Levi & Reuter, 2014). But it also limits legitimacy. Without democratic processes, thorough impact analysis, and proper solutions to concerned constituents, the soft law standard-setting can be viewed as a profound governance issue pertaining to accountability, proportionality, and due process (Pavlidis, 2022; Case-Ruchala and Nance, 2020). The same processes which contribute to the quick convergence and responsiveness may introduce structural tensions between effectiveness, sovereignty, and regulatory legitimacy in the AML and CTF governance structure (Sharman, 2011).
Soft Law as "Binding" Normative Authority
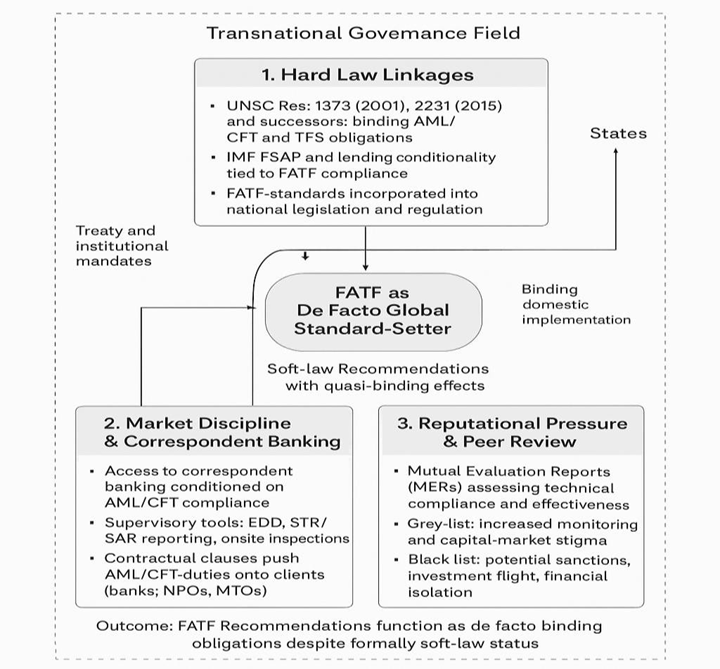
There is a theoretical conflict in the normative authority of the FATF. FATF does not have any legal status in the international law. FATF Recommendations are not treaty documents; FATF does not have the capacity to enforce compliance through sanctions; FATF is not obligatory or by invitation and its membership is voluntary (Turner, 2014). Still, FATF is a de facto standard-setter having normative binding authority (Halliday, Levi & Reuter, 2014). This authority is a result of three mechanisms that are interconnected.
The former comprises of formal hard law linkages. The implementation of the United Nations Security Council Resolutions 1373 (2001), 2231 (2015), and other resolutions based on the counter-terrorist financing rules should be applied in accordance with the FATF standards to be implemented pursuant to AML and CFT standards and be substantially able to consolidate soft law (UNSC, 2001; UNSC, 2015). It is also integrated in FATF compliance within the reviews of Financial Sector Assessment Program (FSAP) by the International Monetary Fund (IMF), frequently tying AML and CFT reforms to financial sector conditionalities (IMF, 2023). These institutional linkages assist in changing FATF Recommendations into de facto legal standards as opposed to aspirational standards (Turner, 2014).
Second, there are market discipline and the correspondent banking restrictions, which are great compliance drivers. Compliance with AML and CFT standards will only enable banks to have access to international networks of correspondent banks which are crucial in cross-border financial dealings (Sharman, 2011). The tools, which are used by the supervisory authorities, include Suspicious Activity Reporting (SAR) requirements and Enhanced Due Diligence (EDD), developing indirect or rather private forms of enforcement (FATF, 2023). By doing so, the financial institutions are legally required to have their contractual and regulatory duties transferred to AML and CFT compliance systems, which are not enforced by the state directly (Halliday, Levi and Reuter, 2014).
Third, compliance is reinforced by reputational processes and peers pressure via self-evaluation. Central instruments of governance are provided by mutual evaluation reports (MERs), which are performed by the FATF (FATF, 2024). Those jurisdictions, which fail to comply, face so-called grey-listing (greater control) or black-listing (demands on counter-measures and financial isolation), which is a powerful source of reputational pressure (Case-Ruchala and Nance, 2020). Though these peer review processes are officially non-binding, they address themselves as quasi-hard law through normative pressure and financial outcasting (Turner, 2014; Case-Ruchala and Nance, 2020). Three mechanisms change FATF soft law into de facto binding authority as explained in Figure 2: (1) hard law linkages (UNSC/IMF), (2) market discipline (correspondent banking/EDD), and (3) reputational peer pressure (merrs/grey-listing), which, in combination, present compliance pressures on states and financial institutions.
This is an example of what is referred to as regulatory capture via collegiality by Braithwaite (Braithwaite, 2008): Peer review establishes insider and outsider statuses, whereby compliant jurisdictions police non-compliant jurisdictions and enforcement is internalized into transnational expert networks (Halliday, Levi & Reuter, 2014; FATF, 2024). This not only distributes the burden of enforcement, but also creates power concentrated in the hands of the technical elites who are not answerable to any democratic office (Sharman, 2011; Pavlidis, 2022).
Compliance Theory and Norm Internalization
To understand why states adhere to soft law without hierarchical enforcement, it would be necessary to shift beyond the rationalistic analysis of costs and benefits. The norm lifecycle theory by Finnemore and Sikkink theorizes that norm emergence, cascade, and internalization can be achieved through different mechanisms (Finnemore & Sikkink, 1998). Rationalist compliance mechanisms are those in which states compute that the benefits of compliance (access to correspondent banking, favorable investor ratings, IMF funding) outweigh the costs (investment in institutional capacity, regulatory burden, sovereignty concerns) (Sharman, 2011; Turner, 2014). This coerced compliance explains why states adopt AML and CFT laws even when domestic capacity constraints persist, as the external economic and reputational incentives make non-compliance more costly (Case-Ruchala & Nance, 2020; IMF, 2023).
Constructivist processes work by the means of internalization of norms and professional socialization. Financial regulators internalize AML and CFT standards by engaging in FATF training regimes, attending regional FSRB expert groups or through mutual evaluation processes, rather than feeling the pressure to comply (Halliday, Levi & Reuter, 2014; FATF, 2024). This norm cascade underlines the reason why FATF standards are likely to be attained quickly without direct material inducement since regulators are considering them a part of the modern financial governance (Finnemore and Sikkink, 1998; Sharman, 2011). Both processes work in parallel in an analytical manner. An excellent example of such a complicated interaction is Pakistan: the acceptance of the FATF standards was done with the pressure of coercion (grey-listing and IMF conditionality), but the implementation lapses remained because of the low internalization of norms through domestic institutions (FATF, 2024; IMF, 2023). On the contrary, numerous advanced jurisdictions institutionalised strict AML and CFT frameworks by constructivist routes by incorporating global financial crime prevention standards into the regulatory culture and profession (Halliday, Levi and Reuter, 2014; Turner, 2014).
The Hard Law Foundation and Soft Law Superstructure:
Treaty Architecture: From Vienna to Contemporary Conventions
The hard law foundation comprises three principal treaty instruments establishing binding international obligations which include:
Article 3 of Vienna Convention (1988) set up the original international criminalization requirement of ML (laundering of proceeds of drug trafficking, under strict predicate crime restriction) (Vienna Convention, 1988). Article 3 obligated states to criminalize ML; Article 4 obliged confiscation and forfeiture of assets; Article 7 obliged MLA (Vienna Convention, 1988). The importance of Vienna was to acknowledge proceeds concealment as a criminal offense of international character that needs collaborative efforts (UNODC, 2023). Nevertheless, its narcotics-particular predicate-based crime was insufficient when organized crime became diversified (Halliday, Levi & Reuter, 2014).
Palermo Convention on Transnational Organized Crime (2000) broadened criminalization to proceeds from all serious crimes (defined as offenses punishable by minimum 4-year imprisonment) (Palermo Convention, 2000). Article 6 required comprehensive criminalization of ML; Article 12 mandated confiscation; Protocol on Trafficking in Persons established additional predicate crimes (Palermo Convention, 2000). The importance of Palermo was the acknowledgement of transnational nature of organized crime and the need to provide it with a coordinated legal system (UNODC, 2023). Nevertheless, the implementation studies point to the existence of unresolved gaps in confiscation implementation especially asset recovery in the developing countries (UNODC, 2023; FATF, 2024).
UNCAC (2003) incorporated corruption-predicate criminalization recognizing that corruption operations tend to launder through financial systems (UNCAC, 2003). Chapter III (Criminalization and Enforcement), Article 23, requires criminalization of laundering of proceeds of corruption; Chapter V (Asset Recovery) provides mechanisms of cross-border asset identification and seizure (UNCAC, 2003). UNCAC represents the most comprehensive transnational asset recovery framework, but effectiveness is constrained by jurisdictional fragmentation and the limited institutional capacity of developing countries (UNODC, 2023; Sharman, 2011). ICSFT (1999) not only criminalized the laundering of terrorist-derived proceeds, but criminalized terrorist financing itself in Article 2 (ICSFT, 1999). Financing of terrorist acts was further reinforced through related obligations under the Convention (ICSFT, 1999; UNSC, 2001). In the wake of 9/11, ICSFT was incorporated into an overall AML and CFT system via interpretive correlations and domestic laws encompassing both money laundering and terrorist financing crimes (UNODC, 2023; FATF, 2023). These agreements form legal commitments that are enforceable by legal means (dispute settlement, countermeasures, non-performance repercussions) (Vienna Convention on the Law of Treaties, 1969). However, they also operate under a soft law superstructure as essential determinants of implementation within the broader FATF-centered governance architecture (Halliday, Levi & Reuter, 2014; FATF, 2024).
The FATF Soft Law Superstructure
The operational center of the regime is the Forty Recommendations of FATF that were first issued in 1989 and revised in 1992, 1996, 2003, 2012, 2023 and have no legal binding nature whatsoever (FATF, 2023). The Recommendations are used to tackle: customer due diligence (CDD), Know Your Customer (KYC), Suspicious Activity Reporting (SAR), record-keeping, international cooperation, asset confiscation, and institutional responsibility (FATF, 2023). The 2012 revision explicitly introduced the counter-terrorist financing framework, making it parallel (FATF, 2012). FATF was able to respond to the evolving needs of its members through the 2023 revision which focused on virtual assets, financing weapons of mass destruction illicitly, as well as environmental crime predicate criminalization, which reveals its dynamic ability to respond to evolving needs without formal amendment procedures (FATF, 2023; Turner, 2014). The interpretive power of FATF goes through: (a) Glossary that creates standard terms; (b) Technical guidance on Recommendations implementation by Interpretive Notes; (c) Mutual Evaluation Methodology which forms assessment criteria; (d) Typologies reports which point to criminal methodologies and institutional weaknesses (FATF, 2023; FATF, 2024). This interpretive apparatus establishes de facto binding norms even where there is formal status of soft law (Halliday, Levi & Reuter, 2014).
The 2013 methodology reform proved critical to governance architecture (FATF, 2013). Prior to 2013, FATF assessed only technical compliance with Recommendations. The revised methodology introduced 11 "Immediate Outcomes" measuring effectiveness: (1) ML and TF risk understanding; (2) international cooperation; (3) confiscation and proceeds recovery; (4) threat-based AML/CFT policies; (5) AML/CFT institutional framework; (6) financial intelligence; (7) ML investigation and prosecution; (8) proceeds-generating crime investigation; (9) TF investigation and prosecution; (10) cross-border movement of currency; (11) WMD proliferation financing prevention (FATF, 2013; FATF, 2024). Such a change in technical compliance to actual crime prevention outcomes theoretically re-orientated the regime towards quantifying real crime prevention impact instead of legal formalism (FATF, 2013). However, empirically, the effectiveness distinction exists: the rating of the average effectiveness of 28 percent around the world (2024) versus 66 percent technical compliance (FATF, 2024). This disconnect demonstrates inherent implementation capacity limitations that are especially acute in the developing jurisdictions (FATF, 2024; Sharman, 2011).
Compliance Without Operational Effectiveness:
Evidence of the Compliance-Effectiveness Gap
The biggest observation that the FATF made in the analysis of the 2013-2024 mutual evaluation database is a critical lack of balance between legal frameworks and its reality (FATF, 2024). Although this fourth round of reviews (which ended in late 2024) resulted in an astronomical growth in legislative uptake, in practice, it has been much less effective (FATF, 2024).
Technical Compliance Average: 66% (ranging from 20% to 95% across jurisdictions) (FATF, 2024)
Effectiveness Average: 28% (ranging from 0% to 75% across jurisdictions) (FATF, 2024)
This 38% point disparity is not a coincidental distribution: this disparity is highly linked with indicators of economic development (Basel AML Index, 2024). The Basel AML Index 2024 shows that high-income OECD nations have the average effectiveness of 60% in Immediate Outcomes, and low-income countries have the average effectiveness of 15-20% (Basel AML Index, 2024). The average effectiveness is at 30-40% in middle-income (such as Pakistan, Mexico, Argentina) even though they reached 60% technical compliance (FATF, 2024; Basel AML Index, 2024). Peculiar Immediate Outcomes demonstrate the especially low level of effectiveness:
IO7 (ML Investigation and Prosecution): FATF mutual compliance as well as academic commentary demonstrates significant differences between high technical compliance (Recommendation 3 criminalization of ML) and far weaker effectiveness to IO7 (ML investigation and prosecution), with many countries having a small number of ML cases and some countries focusing on self-laundering or treating ML as an add-on to predicate crimes (FATF, 2024; Halliday, Levi and Reuter, 2014). In Pakistan, despite having ML criminalization statute (AML Act 2010, amended 2015, 2019 and 2020), evaluations and policy analyses consistently describe ML enforcement as limited relative to its risk profile, with relatively low effectiveness ratings and a small number of convictions compared with investigations (FATF, 2024; IMF, 2023).
•IO9 (TF Investigation and Prosecution): is widely recognized as one of the weakest-rated Immediate Outcomes in mutual evaluations, with very few countries achieving "High" effectiveness (FATF, 2024). A 2023 IMF study on countering terrorist financing notes that only four countries had achieved a "High" rating on IO9, and even "Substantial"-rated countries often showed relatively low numbers of TF investigations and prosecutions compared with their stated risk (IMF, 2023).
•IO11 (WMD Proliferation Financing Prevention): 8% average effectiveness - The least-developed outcome area, with 65% of jurisdictions rated at "low" effectiveness level (FATF, 2024). This represents critical governance failure as WMD proliferation financing constitutes existential security threat (UNSC, 2015; FATF, 2024).
Three important findings are provided in this effectiveness paradox.
First, Capability of Legislation Enforcement: Most of the developing nations have implemented AML and CFT laws in order to be technically compliant with FATF requirements, yet they still have restricted prosecutorial capacity, lack of specialized financial-crime personnel, and inadequate institutional coordination, which restrict substantive enforcement (FATF, 2024; Sharman, 2011). According to mutual assessments and analysis of FATF, despite more and more frequent laws against money laundering, the investigative and prosecution and penalty success rate against single money-laundering offenses has been found to be low in most jurisdictions, and the global performance in that regard has been estimated to be around one-fifth of the projected effect (FATF, 2024; Halliday, Levi & Reuter, 2014).
Second, Institutional Capacity Constraints Are Binding Constraints: Structural resource constraints can only be defeated by legal reform (IMF, 2023; Sharman, 2011). With the spread of the functions of AML and CTF across the agencies, including the Federal Investigation Agency, State Bank, Financial Monitoring Unit, and provincial governments, there are still coordination issues that cannot be sorted out without the institutional reorganization (FATF, 2024).
Third, The Political Economic Factors Limit Legal Capacity: In those countries where the level of corruption is high or where the implementation of AML and CFT can jeopardize the interests of fully established financial markets, governments can officially follow FATF standards but limit de facto implementation (Sharman, 2011; Case-Ruchala & Nance, 2020). This aspect was identified in the 2023 mutual evaluation of Lebanon: the indicators of effectiveness of about 15% in a variety of outcomes showed limited political motivation to act resolutely against politically affiliated financial networks, despite the established legal frameworks (FATF, 2024).
The Compliance Pressure and Sovereignty Paradox
The effectiveness gap poses a basic sovereignty problem: just how far does FATF compliance pressure undermine state institutional autonomy and democratic self-determination? (Drezner, 2007; Zurn, 2018). This question demonstrates a paradox of the AML and CFT regulation. On the one hand FATF compliance pressure is a form of regulatory imperialism that impairs the jurisdictional autonomy (Nance, 2018). Small developing nations have stark choice, including either implementing FATF standards or being pushed to the periphery as a grey and black-listed country, receiving restricted correspondent banking access, and conditionality in IMF lending (IMF, 2022; World Bank, 2023). This coercive device organized with the assistance of mutual evaluation, follow-up measures, and reputational ramifications of a state imposes what could be referred to as a kind of soft coercion that is functionally similar to the traditional sanctions in restricting the autonomy of state behavior (Simmons, 2009; Kelley, 2017).Conversely, the effectiveness gap posits that FATF pressure fails to penetrate the institutional capacity constraints of states regarding their behavioral autonomy (FATF, 2024). The states practically comply with the FATF standards, but institutional frameworks in place do not facilitate effective implementation (Andrews, 2013). This produces the illusion of complying, but not changing any behavior the way it is really practiced, what scholars call symbolic compliance or decoupling between formal adoption and the real practice application (Meyer and Rowan, 1977; Hafner-Burton and Tsutsui, 2005).
The path of Pakistan is the most striking demonstration of this paradox. In June 2018, Pakistan was greylisted due to poor AML and CFT compliance (in particular, insufficient TF investigation capability) (FATF, 2018). The grey-listing posed a threat to IMF bailout programs and correspondent banking relationships-existential threats to the financial system of Pakistan (IMF, 2019; World Bank, 2022). Pakistan, in its turn, implemented thorough legislative amendments (AML Amendment Act of 2010, amended 2020; ICSFT incorporation; expansion of Financial Monitoring Unit) that surpasses the 40 Recommendations by FATF in technical compliance (APG, 2021; FATF, 2024). However, Pakistani mutual evaluation follow-up reports (2021-2023) discovered that significant improvements in effectiveness lagged much behind technical compliance improvements (APG, 2023). Why? Institutional constraints, including that the FIA does not specialize in financial crimes; State Bank supervisory ability is limited; inter-agency coordination systems are not endowed with legislative power; political influence limits investigation of politically related parties (APG, 2021; Transparency International, 2023). The solutions to these institutional limitations cannot be solved by legislation only, but the FATF framework offers limited structured capacity-building enforcement beyond assessment mechanisms (World Bank, 2023; IMF, 2022). This demonstrates the sovereignty paradox: FATF pressure manages to create compliance pressures (hard institutional change) but does not result into effectiveness (soft institutional change that requires internalization of AML and CFT standards into the bureaucratic culture) (Zürn, 2018; Andrews, 2013). The coerced change in behavior occurs without internalization of the norms consensually by the regime (Finnemore & Sikkink, 1998; Meyer & Rowan, 1977).
Contemporary Challenges:
Cryptocurrency Regulation and the Boundaries of Transnational Authority
Virtual assets (cryptocurrencies, tokens, stablecoins) represent the most significant governance challenge to AML and CFT regime's traditional architecture (Arner, Auer & Frost, 2020; Zetzsche, Buckley, Arner & Barberis, 2020). These digital assets operate across territorial boundaries, employ cryptographic concealment, and generate transaction volumes exceeding traditional banking oversight capacity (UNODC, 2022; BIS, 2023).
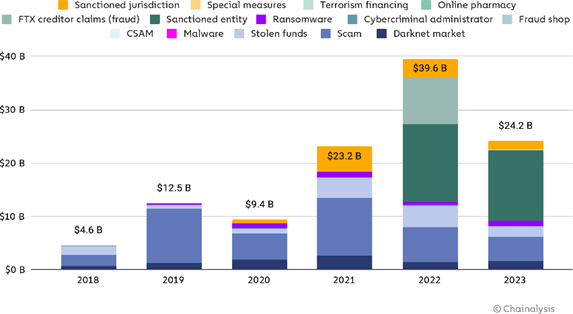
Source: The data are drawn from Chainalysis' 2024 Crypto Crime Report
Figure 3 shows' estimates of the total value of cryptocurrency received on addresses identified as illicit between 2018 and 2023 as a breakdown by the main categories of criminal activities (Europol, 2023). According to Figure 3, during 2018-2022, the total value of funds transferred to illicit addresses grew significantly and reached its peak in 2022, and then somewhat decelerated in 2023 (Europol, 2023; BIS, 2023). The reaction of FATF is a good illustration of both the adaptive ability and the long-term constraints of the two regimes. The revised version of the Recommendations (R.15, revised 2023) introduced the regulation of VASPs requiring the same CDD, transaction monitoring, and reporting requirements as traditional financial institutions (FATF, 2019; FATF, 2023). The FATF has a so-called travel rule, where VASPs are required to transfer customer information in a manner that is reminiscent of SWIFT banking protocols (FATF, 2019).
Implementation is considered to have crucial loopholes. Peer-to-peer transfers can also be facilitated by DeFi arrangements that are not as reliant on traditional intermediaries, and that some services that cannot be linked to any identifiable party that has control and influence over them, today, would certainly not fit the clear AML and CFT requirements in most jurisdictions (OECD, 2022; European Central Bank, 2023). The recent work by FATF on virtual assets and DeFi has identified the high risks of ML and TF presented by such services and the need to find responsible persons in purportedly decentralized arrangements, but regulators have encountered practical challenges in implementing these requirements where governance and control have become largely decentralized (FATF, 2023; IOSCO, 2022). These illustrations highlight the gaps in global standards of AML and CFT as well as systemic weaknesses (BIS, 2023). Permissive jurisdictions become a target to centralized operations, whereas permissionless DeFi promotes decentralized laundering (Europol, 2023; OECD, 2022). Furthermore, improved international coordination is critical towards substantive compliance (UNODC, 2022; IOSCO, 2022).
Table 1 DeFi Protocols Most Associated with Illicit Activity
Category/Examples
Why associated with risks
Illicit use examples
DEXs (e.g., Uniswap, PancakeSwap)
Largest volume of swaps for layering illicit funds; no KYC by design.58
96%+ of sanctioned DeFi theft proceeds laundered via DEXs.59
Cross-chain bridges (e.g., AnySwap, Ronin)
Enable "chain hopping" to obscure
trails across blockchains.
Used in hacks/exploits for rapid fund movement.60
Mixers/tumblers (e.g., Tornado Cash)
Explicitly designed for privacy/obfuscation; sanctioned for sanctions evasion.61
Only 2% of some illicit flows, but high-profile for laundering.62
As an example, Tornado Cash became known as a proponent of ML because of its fundamental structure, a decentralized cryptocurrency mixer on Ethereum (and subsequent chains), which removes the identifiable connection between sender and receiver address on public blockchains (U.S. Department of the Treasury, 2022; OFAC, 2022). Regulatory progress still fails to limit the use of illicit cryptocurrency flows, and mixers and other means are already used to bypass the opportunities provided by sanctioned services, such as Tornado Cash (FBI, 2023; UNODC, 2024). The charts 4 below demonstrate the main trends in mixers and methods of laundering (Interpol, 2023; Global Financial Integrity, 2023).
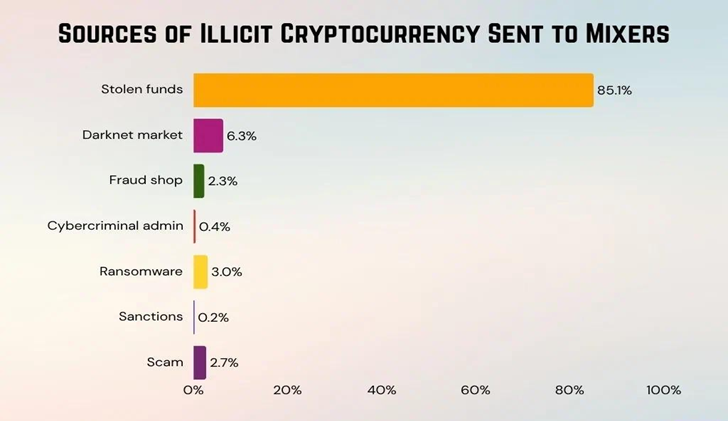
Source: CoinLaw.io, 2026
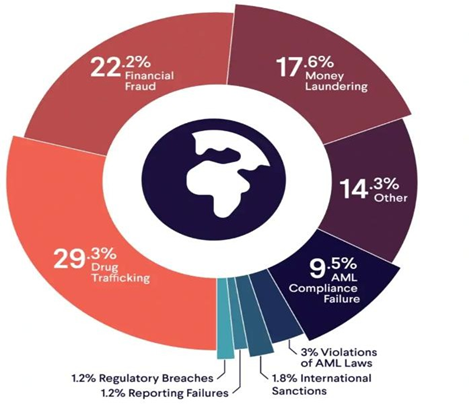
Second, regulatory fragmentation, such as cryptocurrencies operates globally yet regulation remains jurisdictionally segmented, creating regulatory arbitrage opportunities (Financial Stability Board, 2023; G7, 2022). Third, technological capacity constraints, such as most jurisdictions lack blockchain analytics expertise; cryptocurrency transaction monitoring remains imperfect; and zero-knowledge proofs create privacy-preserving transaction structures evading monitoring (World Economic Forum, 2023; FATF, 2021). Illicit crypto activities span multiple crime types, with AML failures enabling significant portions (Chainalysis, 2023; Europol, 2022). Figure 5 Presented global breakdown of illicit activities by AML failure type (Global Initiative Against Transnational Organized Crime, 2023). Drug trafficking leads to 29.3% (EMCDDA, 2023; UNODC, 2023).
Countries frequently characterized as having relatively liberal crypto-regulations, that is, light taxation, few licensing obstacles, low enforcement levels, or lax innovation-enabling frameworks are the following, all of which are based on 2025-2026 analysis. Table 2 shows jurisdictions, which have rather relaxed crypto structures that allow arbitrage.
Table 2 Jurisdictions with Lenient Crypto Regulations (2025-2026)
Country/Territory
Why considered lenient
Cayman Islands
No income, capital gains, or corporate tax on crypto; minimal capital requirements for exchanges/custodians; fast licensing under Virtual Asset Service Providers Act with no physical presence needed.
United Arab Emirates (UAE)
Zero personal income tax on crypto gains; clear but business-friendly licensing via VARA (Dubai); tax exemptions attract exchanges and traders.
Panama
Territorial taxation (no tax on foreign crypto income); no minimum capital for early-stage projects; fast registration with low barriers for crypto firms.
El Salvador
Bitcoin legal tender with full tax exemption on crypto gains; government adoption reduces restrictions; minimal regulatory burden for BTC-related activities.
Costa Rica
Low taxes and flexible rules for crypto startups; no minimum capital; ideal for MVP-stage projects avoiding fiat integration.
Germany
Hold crypto for 12+ months and pay zero tax - rare for an EU country. In a high-tax nation like Germany, this setup is surprisingly generous.
Such fragmentation incentivizes firms to relocate to low-oversight venues, complicating cross-border enforcement of FATF standards (OECD, 2023; Financial Action Task Force, 2024). Table 1 shifts focus on DeFi, where pseudonymity enables money laundering irrespective of jurisdiction (European Union Agency for Law Enforcement Cooperation, 2024; Bank for International Settlements, 2024). Basel AML Index 2024, there are still gaps in the technical advances (Basel Institute on Governance, 2024). According to blockchain reports, in 2024, illicit crypto inflows were reported to be 40.9B (down after the 2022 peak), but crypto laundering volumes increased 23 percent YoY with the expansion of DeFi/mixers (TRM Labs, 2025; Elliptic, 2025).
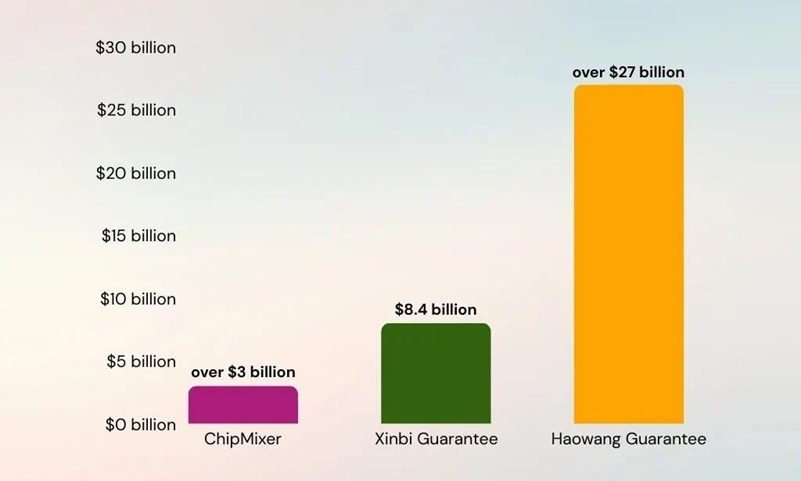
In 2024, crypto laundering occurred to the tune of 40 billion (TRM Labs, 2025). This is a sign of basic confrontation. The soft law framework of FATF is prepared to work with the jurisdictional partnership and enforcement competency; the decentralized structure and the technological advancement of cryptocurrency surpass the conventional enforcement systems (International Organization of Securities Commissions, 2024; Financial Stability Institute, 2024). Only 40 of 138 jurisdictions assessed were "largely compliant" with FATF crypto standards as of April 2025, with crypto contributing to the rise in laundering illicit funds (FATF, 2025). Traditional mixers face crackdowns, driving adoption of chipmixers and cross-chain services (U.S. Department of Justice, 2024; Europol, 2024). Figure 6 illustrated common ML methods in cryptocurrency. Mixers exceed $27B; chipmixers reach $8.4B (Elliptic, 2025; TRM Labs, 2025). These alternatives sustain $30B+ annual laundering, evading VASP-centric regulation (Chainalysis, 2025; Global Financial Integrity, 2024).
De-risking, Financial Inclusion, and Unintended Governance Consequences
AML and CFT regime have generated significant unintended consequences, particularly "de-risking" financial institutions abandoning relationships with entire customer categories (non-profit organizations, politically exposed persons, developing country banks) perceived as high-risk to mitigate regulatory liability (World Bank, 2015; Financial Stability Board, 2022). There are unintended effects of AML and CFT regimes, including de-risking, whereby financial institutions cut down on relationships with NPOs, PEPs, and banks in the developing countries to evade the liability of such relationships (United Nations, 2022; International Monetary Fund, 2024). This is attributed to high fines on violations, and fines of 2025 amount over 1.23 billion in the first half of year alone (AML Intelligence, 2025; Refinitiv, 2025). Table 3 showed current fines on the failure to enforce AML that encourages conservative de-risking even among systemically important banking institutions dealing with risky clients (Bank for International Settlement, 2024; Wolfsberg Group, 2023).
Table 3 Major 2025 Bank AML Fines Linked to De-Risking Pressures.
| Bank/Institution | Penalty | Regulator/Key Findings | De-risking Link | |||
| TD Bank (US) | $3B | DOJ/FinCEN: Chronic AML failures, inadequate high-risk monitoring (2014-2023). | Contributed to de-risking via heightened scrutiny on risky clients. | |||
BMO Harris (US) | $1.5B | US authorities: Poor SAR reporting, transaction monitoring gaps. | Similar pressures from enforcement on high-risk flows. | |||
Nationwide Building Society (UK) | £44M | FCA: Systemic financial crime control deficiencies. | Weak controls drove preemptive de-risking. | |||
Barclays (UK) | £39.3M | FCA: Failure to monitor high-risk clients. | Explicit high-risk monitoring lapse. | |||
Monzo Bank (UK) | £21M | FCA: Inadequate onboarding, risk assessment, monitoring (2018- 2020). | Fintech growth exposed CDD gaps. | |||
| J.P. Morgan SE (Germany) | €45M | BaFin: Delayed STR filing (2021- 2022). | Escalation failures amplified liability fears. | |||
Source: Adopted from various web sources
No cases directly fined banks for de-risking itself (FATF discourages blanket terminations); penalties targeted control weaknesses that prompt de-risking as risk mitigation (Financial Conduct Authority, 2023; U.S. Federal Reserve, 2024). These cases demonstrated how monitoring lapses incentivize broad client terminations rather than nuanced risk management (Office of the Comptroller of the Currency, 2024; European Banking Authority, 2023). To minimize risk of violation, banks adopt conservative policies, such as closing accounts of nonprofits despite charitable registration; refusing correspondent banking relationships with developing country banks despite legitimate operations; imposing EDD on remittance providers and money transfer operators (World Bank, 2023; SWIFT Institute, 2024). De-risking disproportionately impacts nonprofits, severing legitimate funding channels despite FATF risk-based guidance (Charity & Security Network, 2023; OECD, 2024). Figure 7 De-risking cycle represented regulatory cascade from FATF to delayed NPO donations (Center for Global Development, 2023; United Nations Development Programme, 2024).
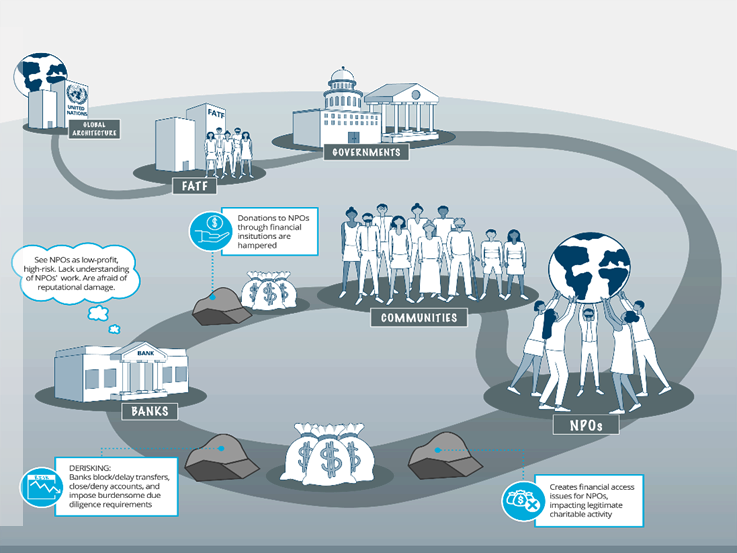
This cycle makes the AML objectives futile as it forces aid to informal channels that enhance the exclusion of vulnerable populations even further (Overseas Development Institute, 2023; International Rescue Committee, 2024). This de-risking has produced humanitarian effects which have been captured by the World Bank and humanitarian bodies in abundance (World Bank, 2022; United Nations Office for the Coordination of Humanitarian Affairs, 2023). The report of the UN Office on Drugs and Crime (2023) established that de-risking has lowered the flow of remittance to third world countries by a range of 5-8 million dollars, and this has deprived the recipient economies of millions of dollars in development aid and household incomes (UNODC, 2023). The de-risking crisis of Kenya in 2015-2017, in which international banks cancelled accounts with Kenyan money transfer companies, had an effect on Kenyan remittance flows which have been 3% of GDP (Central Bank of Kenya, 2018; African Development Bank, 2019).
The de-risking phenomenon indicates inherent governance conflict: AML and CFT regime maximizes security (removing illicit finance) at the expense of financial inclusion and development goals (Alliance for Financial Inclusion, 2022; United Nations Development Programme, 2023). The 2013-2023 guidance of FATF was dealing with de-risking peripherally; the revision of the 2023 Recommendation (R.1 on national AML and CFT policies) included proportionality language that implied that the risk-based approach was not to be used in an indiscriminate manner (exclusiveness) (FATF, 2023). However, implementation is still ineffective because the regulatory bodies focus on enforcing compliance, rather than providing universal access to financial markets (Financial Stability Institute, 2023; G20 Global Partnership for Financial Inclusion, 2024).
Towards Reforms:
Identifying the Legitimacy Deficit
The legitimacy crisis of AML and CFT regime is based on three structural deficits, including the primary one, the democratic accountability deficit (Held & Koenig-Archibugi, 2005; Buchanan & Keohane, 2006). FATF standard-setting is done by plenary and working groups in which it engages state representatives and observers of the private sector, but has no transparency mechanisms, no procedures of consultation with the public, or any requirement of an impact assessment (Tallberg, Bäckstrand & Scholte, 2018; Scholte, 2011). The developing countries, which incur great compliance costs, have formal seats but low influence as compared to the standard-setters (Woods, 2006; Vestergaard & Wade, 2013). FATF plenary/working groups have an approximate membership of 200 (39 jurisdictions + observers) members, and the input of the private sector is provided through Consultative Forum, although critics have criticized the regime as lacking in open decision-making, having few consultations with the public, and lacking any form of mandatory ex ante impact assessment, which is creating a democratic deficit (Global Administrative Law Project, 2022; Transparency International, 2024). The regime is an example of what scholars refer to as unaccountable global governance norm-setting by unelected technical experts without any democratic accountability mechanisms (Slaughter, 2004; Zürn, 2018).
Second, lack of protection of rights. AML and CFT standards (terrorist organizations in particular) pose a threat to rights: financial exclusion can result in lack of access to important services; sanctions (targeting terrorist groups) can inadvertently lead to freezing assets of relatives without due process protections; proportionality analysis is inadequately developed within the FATF framework (Human Rights Watch, 2023; International Commission of Jurists, 2022). FATF proportionality is limited (Amnesty International, 2023). UN Global Counter-Terrorism Coordination Compact guidance (2025) identifies CFT harms including property deprivation and vulnerable population exclusion (United Nations, 2025). UN Special Rapporteur Fionnuala Ní Aoláin (2023 essay) and others document discriminatory exclusion and property rights violations (Ní Aoláin, 2023; Office of the High Commissioner for Human Rights, 2024).
Third, effective accountability deficit. Mutual evaluation process assesses compliance with FATF Recommendations but provides limited accountability for governance outcomes (Koppell, 2010; Grant & Keohane, 2005). Countries achieving technical compliance without effective improvements face follow-up procedures but lack binding remedies (OECD, 2024). Conversely, FATF itself faces no accountability for regime's effectiveness gaps despite prescriptive authority over global financial governance (Keohane, 2011; Zürn, 2018).
The Effectiveness-Legitimacy Test: A Reform Framework
To address these deficits, this article proposes an "Effectiveness-Legitimacy Test" as reform framework governing FATF standard-setting and implementation evaluation (Majone, 1999; Bovens, 2007). The test comprises three integrated components such as:
Component 1: Effectiveness Threshold: Before FATF recommends new standards or enhanced obligations, prospective impact assessment should estimate: (a) anticipated ML/TF disruption effects (quantified through typology studies, pilot programs); (b) implementation costs for target jurisdictions (disaggregated by development level); (c) anticipated unintended consequences (de-risking effects, financial inclusion impact, burden on non-financial businesses and professions) (OECD Regulatory Policy Outlook, 2021; World Bank, 2021). Standards failing to meet threshold effectiveness should be redesigned or abandoned. This would require FATF to develop more rigorous cost-benefit methodology than currently exists; most FATF Recommendations lack quantified effectiveness estimates (Sunstein, 2018; Radaelli, 2007).
Component 2: Legitimacy Procedure: The FATF standard-setting process must include: (a) a venue to take into consideration jurisdictional comments especially on developing nations; (b) impact analysis on risky populations and human rights safeguards; (c) proportionality analysis to ensure that obligations reflect the real level of threats; and (d) capacity-building commitment where FATF/IMF/World Bank provide technical assistance on implementation in case the standards are greater than the institutional capacity of jurisdictions (United Nations Development Programme, 2022; World Justice Project, 2023). This would involve institutional reform: development of FATF stakeholder advisory mechanism; establishment of a human rights assessment framework equivalent to mutual evaluations; creation of a capacity-building registry documenting training, technical assistance, and financial support requirements accompanying new standards (Open Government Partnership, 2023; Global Partnership for Effective Development Co-operation, 2022).
Component 3: Accountability Mechanism: The mutual evaluation procedure must be transformed to: (a) make FATF responsible for prescribing non-efficacious and systemic effectiveness standards across jurisdictions; (b) provide binding solutions to nations where mutual evaluation has demonstrated effectiveness gaps notwithstanding formal compliance (capacity-building support instead of simply follow-up reports); (c) assess effectiveness at the regime-level rather than compliance at jurisdiction-level (does AML and CFT regime systematically attain meaningful crime prevention?) (Keohane & Nye, 2003; Mashaw, 2006).
This structure shifts AML/CFT governance from legitimacy-through-technical-compliance to legitimacy-through-effectiveness-and-accountability (Beetham, 2013; Buchanan & Keohane, 2006). Instead of assuming that FATF standards are inherently legitimate when properly adopted, the framework mandates empirical demonstration that standards reduce illicit finance while preserving jurisdictional autonomy and human rights safeguards (Sen, 2009; Habermas, 2001).
Conclusion
The international regime on AML and CTF can be seen as a notable success in the norm diffusion on a transnational level: in 35 years, a decentralized, piecemeal set of bilateral agreements was changed to a globally convergent regime with almost universal jurisdictional coverage. This success supports the ability of soft law to bring about convergence of lawmaking without the authority to bind. But there is investigation that proves that success is not full. The compliance effectiveness gap averaging the difference of 38 percentage points among jurisdictions has shown that legal harmonization is not a sure result in creating functional convergence in crime prevention. States officially embrace the AML and CFT standards without ensuring the adequacy of enforcement practices and institutional frameworks that are operational in nature. This tension is embodied in the sovereignty paradox FATF exercises the authority of de facto regulation without legally possessing the authority to exert control, and produces coerced behavioral change (legal adoption) without producing consensual norm internalization (effective institutional implementation). This brings legitimacy issues and without satisfactory institutional responses.
The focal point of the article is that the governance of AML and CFT needs to shift towards the legitimacy-through-compliance model to rely on the legitimacy through effectiveness framework. This entails: (1) sincere recognition that soft law standard-setting is not democratically accountable; (2) empirical test whether or not standards have the effect of reducing illicit finance; (3) systematic impact analysis of unintended results (de-risking, financial exclusion); (4) willingness to assist developing countries in capacity building and not to exert pressure to comply with the standards; (5) the inclusion of proportionality and human rights considerations in the structure of AML and CFT. There are operationalization principles of these principles that are suggested in the Effectiveness-Legitimacy Test framework. The structure remedies lack of legitimacy by the demand of cost-benefit analysis, public comment processes, impact evaluation, and accountability, and may enhance regime performance by imposing more relevant standards. This would in turn necessitate institutional change at FATF level, greater transparency, and inclusion of multiple stakeholder voices as well as enforce commitment and accountability procedures, which would be challenging in terms of governance. But the other alternative, which is continuity of legitimacy by means of coercive compliance without responsibility is unsustainable. With the spread of digital finance, geopolitics, and constraints in developing countries capacity, AML and CFT governance demands an even higher source of institutional legitimacy than the technical compliance standards could offer. Reform to effectiveness-legitimacy integration is an evolution towards sustainable global financial crime governance that is needed.
References
- African Development Bank. (2019). Remittance flows and financial stability in Africa. https://www.afdb.org
- Alliance for Financial Inclusion. (2022). Balancing AML/CFT and financial inclusion. https://www.afi-global.org
- Ambareen, S., et al. (2023). Early reporting requirements and financial crime regulation. [Journal details not provided].
- Amnesty International. (2023). Counter-terrorism financing and human rights safeguards. https://www.amnesty.org
- Andrews, M. (2013). The limits of institutional reform in development. Cambridge University Press. https://doi.org/10.1017/CBO9781139644667
- Asia Pacific Group on Money Laundering. (2021). Mutual evaluation report: Pakistan. https://www.apgml.org
- Asia/Pacific Group on Money Laundering. (2023). Pakistan follow-up report. https://www.apgml.org
- Arner, D. W., Auer, R., & Frost, J. (2020). Stablecoins: Risks, potential and regulation. BIS Working Papers. https://www.bis.org/publ/work905.pdf
- Basel Institute on Governance. (2024). Basel AML Index 2024 report. https://baselgovernance.org
- Beetham, D. (2013). The legitimation of power (2nd ed.). Palgrave Macmillan.
- Bank for International Settlements. (2024). Global financial regulation report. https://www.bis.org
- Bovens, M. (2007). Analysing and assessing accountability: A conceptual framework. European Law Journal, 13(4), 447–468. https://doi.org/10.1111/j.1468-0386.2007.00378.x
- Braithwaite, J. (2008). Regulatory capitalism: How it works, ideas for making it work better. Edward Elgar.
- Buchanan, A., & Keohane, R. O. (2006). The legitimacy of global governance institutions. Ethics & International Affairs, 20(4), 405–437. https://doi.org/10.1111/j.1747-7093.2006.00043.x
- Case-Ruchala, A., & Nance, M. T. (2020). FATF blacklisting and soft law enforcement dynamics. Review of International Political Economy. https://doi.org/10.1080/09692290.2020.1830831
- Central Bank of Kenya. (2018). Impact of correspondent banking withdrawal on remittances. https://www.centralbank.go.ke
- Chainalysis. (2023). Crypto crime report 2023. https://www.chainalysis.com
- Chainalysis. (2024). Crypto crime report 2024. https://www.chainalysis.com
- Chainalysis. (2025). Crypto crime trends report 2025. https://www.chainalysis.com
- Drezner, D. W. (2007). All politics is global: Explaining international regulatory regimes. Princeton University Press.
- Elliptic. (2025). Crypto laundering and DeFi report 2025. https://www.elliptic.co
- Europol. (2022). Internet organised crime threat assessment. https://www.europol.europa.eu
- Europol. (2023). European financial crime threat assessment. https://www.europol.europa.eu
- Europol. (2024). Cryptocurrency crime trends report. https://www.europol.europa.eu
- Financial Action Task Force. (1990). The Forty Recommendations. https://www.fatf-gafi.org
- Financial Action Task Force. (2012). International standards on combating money laundering and the financing of terrorism & proliferation. https://www.fatf-gafi.org
- Financial Action Task Force. (2013). Methodology for assessing technical compliance and effectiveness. https://www.fatf-gafi.org
- Financial Action Task Force. (2018). Public statement on Pakistan. https://www.fatf-gafi.org
- Financial Action Task Force. (2019). Guidance for a risk-based approach to virtual assets and VASPs. https://www.fatf-gafi.org
- Financial Action Task Force. (2021). Updated guidance on virtual assets. https://www.fatf-gafi.org
- Financial Action Task Force. (2024). Consolidated mutual evaluation report data (2013–2024). https://www.fatf-gafi.org
- Financial Action Task Force. (2025). Virtual asset compliance update report. https://www.fatf-gafi.org
- Financial Conduct Authority. (2023). AML enforcement actions report. https://www.fca.org.uk
- Financial Stability Board. (2022). Evaluation of the effects of de-risking. https://www.fsb.org
- Financial Stability Board. (2023). Global crypto regulation framework. https://www.fsb.org
- Finnemore, M., & Sikkink, K. (1998). International norm dynamics and political change. International Organization, 52(4), 887–917. https://doi.org/10.1162/002081898550789
- Grant, R. W., & Keohane, R. O. (2005). Accountability and abuses of power in world politics. American Political Science Review, 99(1), 29–43. https://doi.org/10.1017/S0003055405051476
- Habermas, J. (2001). The postnational constellation. MIT Press.
- Hafner-Burton, E. M., & Tsutsui, K. (2005). Human rights in a globalizing world. American Journal of Sociology, 110(5), 1373–1411. https://doi.org/10.1086/428442
- Halliday, T. C., Levi, M., & Reuter, P. (2014). Global surveillance of dirty money. Crime, Law and Social Change, 61(3), 307–341.
- Held, D., & Koenig-Archibugi, M. (2005). Global governance and public accountability. Blackwell.
- International Convention for the Suppression of the Financing of Terrorism. (1999). United Nations. https://www.un.org
- International Monetary Fund. (2019). Pakistan country report. https://www.imf.org
- International Monetary Fund. (2022). AML/CFT and financial sector assessments. https://www.imf.org
- International Monetary Fund. (2023). Countering terrorist financing effectiveness report. https://www.imf.org
- International Organization of Securities Commissions. (2022). DeFi and regulatory challenges. https://www.iosco.org
- Jason, S. (2008). FATF and the rise of soft law governance. Journal of Financial Crime.
- Kelley, J. (2017). Scorecard diplomacy. Cambridge University Press. https://doi.org/10.1017/9781316795762
- Keohane, R. O. (2011). Global governance and legitimacy. Review of International Political Economy, 18(1), 99–109. https://doi.org/10.1080/09692290.2011.545222
- Majone, G. (1999). The regulatory state and its legitimacy problems. West European Politics, 22(1), 1–24.
- Meyer, J. W., & Rowan, B. (1977). Institutionalized organizations. American Journal of Sociology, 83(2), 340–363. https://doi.org/10.1086/226550
- Ní Aoláin, F. (2023). Counter-terrorism, sanctions, and human rights. United Nations Special Rapporteur. https://www.ohchr.org
- Organisation for Economic Co-operation and Development. (2022). DeFi and regulatory challenges. https://www.oecd.org
- Organisation for Economic Co-operation and Development. (2023). Crypto-asset reporting framework. https://www.oecd.org
- Pavlidis, G. (2022). FATF and global governance legitimacy challenges. Journal of Financial Regulation.
- Sen, A. (2009). The idea of justice. Harvard University Press.
- Sharman, J. C. (2011). The money laundry. Cornell University Press.
- Slaughter, A.-M. (2004). A new world order. Princeton University Press.
- Sunstein, C. R. (2018). The cost-benefit revolution. MIT Press.
- Teubner, G. (2012). Constitutional fragments. Oxford University Press.
- Turner, N. W. (2014). Soft law and FATF compliance. Journal of International Economic Law.
- United Nations Convention against Corruption. (2003). https://www.unodc.org
- United Nations Office on Drugs and Crime. (2023). World drug report 2023. https://www.unodc.org
- United Nations Security Council. (2001). Resolution 1373. https://www.un.org/securitycouncil
- United Nations Security Council. (2015). Resolution 2231. https://www.un.org/securitycouncil
- Vienna Convention on the Law of Treaties. (1969). United Nations. https://legal.un.org
- United Nations Convention against Illicit Traffic in Narcotic Drugs and Psychotropic Substances. (1988). https://www.unodc.org
- World Bank. (2015). Report on de-risking and correspondent banking. https://www.worldbank.org
- World Bank. (2022). Remittances and financial inclusion report. https://www.worldbank.org
- World Bank. (2023). AML/CFT implementation and development. https://www.worldbank.org
- Zetzsche, D., Buckley, R. P., Arner, D. W., & Barberis, J. (2020). Regulating decentralized finance. University of Hong Kong Law Working Paper.
- Zürn, M. (2018). A theory of global governance. Oxford University Press.
Cite this article
-
APA : Memon, H. A., Malik, G. M., & Kumar, R. (2026). Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks. Global Social Sciences Review, XI(I), 81-101. https://doi.org/10.31703/gssr.2026(XI-I).08
-
CHICAGO : Memon, Hyder Ali, Ghulam Mujtaba Malik, and Ramesh Kumar. 2026. "Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks." Global Social Sciences Review, XI (I): 81-101 doi: 10.31703/gssr.2026(XI-I).08
-
HARVARD : MEMON, H. A., MALIK, G. M. & KUMAR, R. 2026. Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks. Global Social Sciences Review, XI, 81-101.
-
MHRA : Memon, Hyder Ali, Ghulam Mujtaba Malik, and Ramesh Kumar. 2026. "Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks." Global Social Sciences Review, XI: 81-101
-
MLA : Memon, Hyder Ali, Ghulam Mujtaba Malik, and Ramesh Kumar. "Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks." Global Social Sciences Review, XI.I (2026): 81-101 Print.
-
OXFORD : Memon, Hyder Ali, Malik, Ghulam Mujtaba, and Kumar, Ramesh (2026), "Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks", Global Social Sciences Review, XI (I), 81-101
-
TURABIAN : Memon, Hyder Ali, Ghulam Mujtaba Malik, and Ramesh Kumar. "Global AML and CFT Governance: Doctrinal Analysis of Hard Law, Soft Power, and the Sovereignty Clash to Reshape Frameworks." Global Social Sciences Review XI, no. I (2026): 81-101. https://doi.org/10.31703/gssr.2026(XI-I).08